Khyber Pakhtunkhwa · Guide
Insaf Rozgar Scheme – KP Business Loans
Insaf Rozgar Scheme is a Bank of Khyber-administered loan programme, launched by the Khyber Pakhtunkhwa government, and it belongs to government schemes across Khyber Pakhtunkhwa aimed at reducing unemployment. According to BOK’s own eligibility page, it specifically targets permanent residents of KP’s Newly Merged Districts (the former FATA areas) — some general coverage describes it as open to all of KP, but the bank’s own current criteria are narrower, so confirm your district’s eligibility before applying. Loans are interest-free and go toward starting or supporting a micro-scale enterprise. This guide covers eligibility, the guarantor requirement, loan terms, and how to apply.
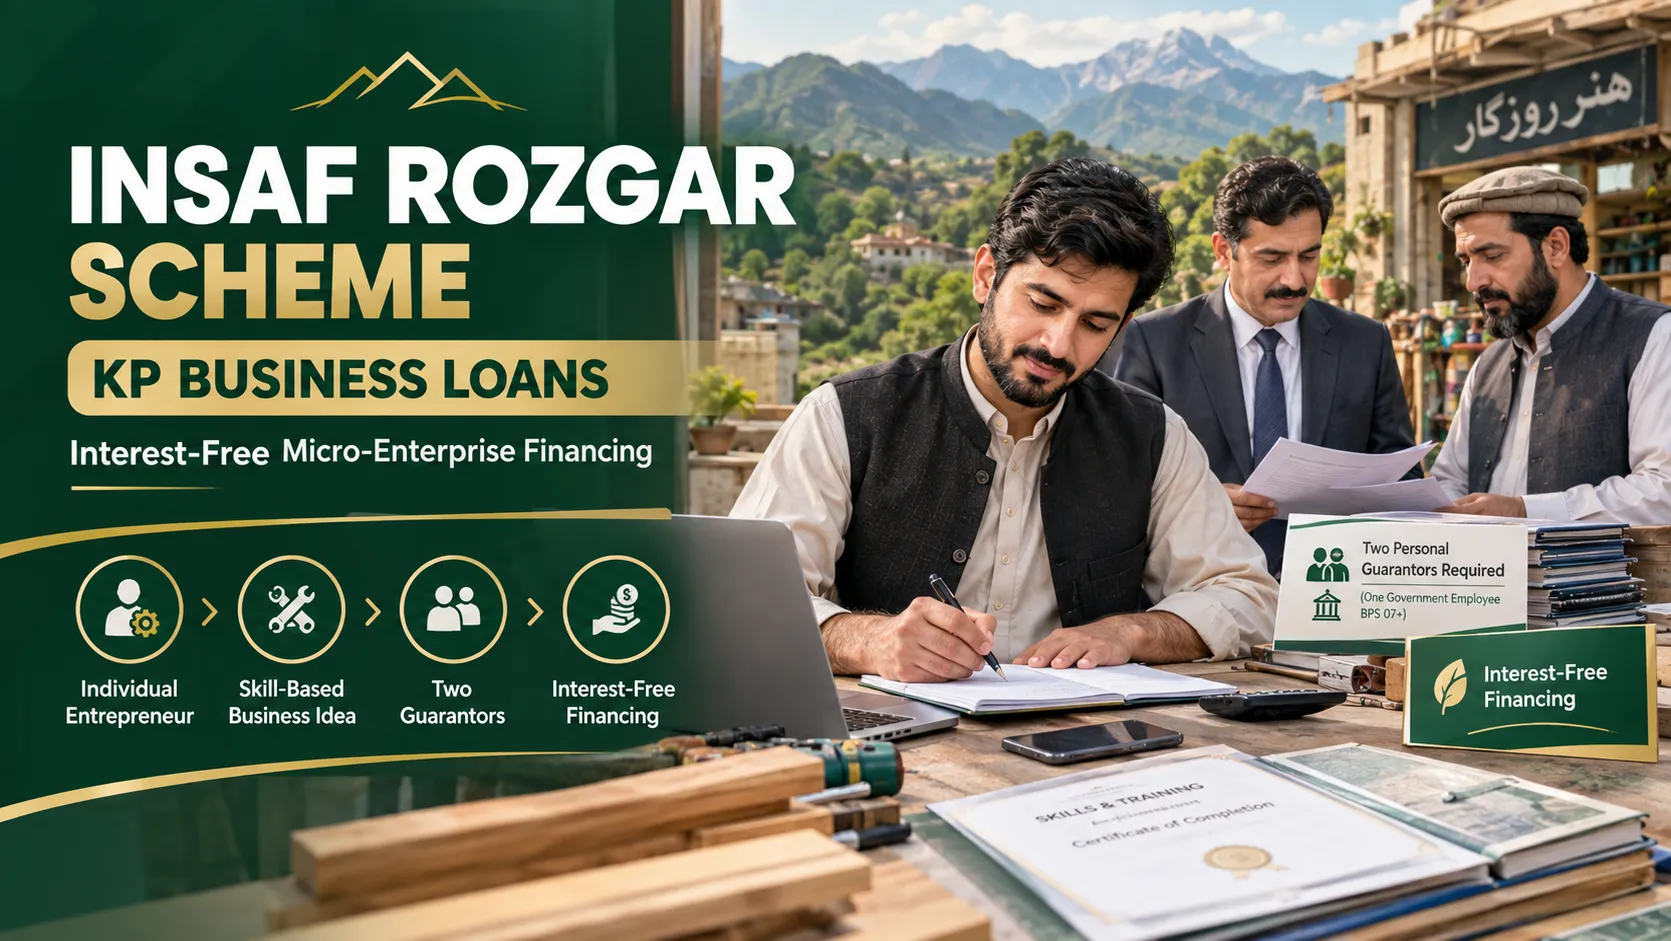
Insaf Rozgar Scheme is a Bank of Khyber-administered loan programme, launched by the Khyber Pakhtunkhwa government, and it belongs to government schemes across Khyber Pakhtunkhwa aimed at reducing unemployment. According to BOK’s own eligibility page, it specifically targets permanent residents of KP’s Newly Merged Districts (the former FATA areas) — some general coverage describes it as open to all of KP, but the bank’s own current criteria are narrower, so confirm your district’s eligibility before applying. Loans are interest-free and go toward starting or supporting a micro-scale enterprise. This guide covers eligibility, the guarantor requirement, loan terms, and how to apply.
Key facts
- Amount / benefit
- Interest-free loans; the exact size depends on assessment of your business plan. Reported figures have varied across phases, from Rs. 50,000 up to Rs. 1 million. For new enterprises, the tenor is 3 years, including a 3-month grace period.
- Who qualifies
- Permanent residents of KP’s Newly Merged Districts with a valid CNIC, resident at their provided address for at least 2 years, aged 18 to 50, with a workable, skills-relevant business idea and two personal guarantors, at least one a government employee of BPS 07 or above.
- How to check / apply
- Confirm your district is covered, then visit your area’s designated BOK branch or Area Office handling Insaf Rozgar applications and submit your documents together.
- Official helpline / portal
- See the guide below
Awamschemes.com is an independent information resource and has no official affiliation with the Government of Khyber Pakhtunkhwa or Bank of Khyber. For official information, use Bank of Khyber’s official portal, bok.com.pk.
What Is Insaf Rozgar Scheme
Insaf Rozgar Scheme was originally announced in 2019, with a second phase launched later offering loans of up to Rs. 1 million to youth in the merged districts. It is separate from Ehsaas Naujawan Programme, which is BOK’s other KP youth-loan product but structured around registered partnerships rather than individual applicants with guarantors. Insaf Rozgar specifically prioritizes unemployed individuals, small traders, and new skilled graduates from vocational or GoKP development programs who lack the capital to start a micro-scale enterprise.
Eligibility for Insaf Rozgar Scheme
According to BOK’s own criteria, you must be a permanent resident of KP’s Newly Merged Districts, holding a valid CNIC, and resident at your provided address for at least 2 years. The age limit is 18 to 50 years. You need a workable, skills-relevant business idea rather than just an intention to start something — BOK explicitly assesses whether the idea is “do-able.” Preference goes to graduates of skilled GoKP development programs or their affiliated institutes, as well as unemployed individuals and small traders already working in a relevant trade.
Guarantor Requirements (Read This Before Applying)
This is where many applicants get stuck, so it’s worth its own section. You need two Personal Guarantors (PGs), and at least one of them must be a government employee of BPS 07 or above — this is a firm requirement, not a preference. Your government guarantor needs to provide a salary slip and a Letter of Comfort from their department confirming their BPS grade. Your private guarantor (if the second guarantor isn’t a government employee) needs documented proof of income plus a signed undertaking on stamp paper. Both guarantors also need two passport-size photographs each, matching the applicant’s own submission.
Before You Visit the Branch: A Preparation Checklist
Most Insaf Rozgar applications that stall do so for a preparation reason, not because the business idea was weak. Work through this checklist before you travel to your branch. First, confirm that your district is currently covered — the scheme runs in the Newly Merged Districts and FR regions — and that you have been resident at your provided address for at least 2 years, with a valid CNIC. Second, write your business plan down in a clear form. BOK assesses whether your idea is “do-able” and relevant to a skill you actually have, so a plan that names your trade, your expected customers, and what the loan will buy is far stronger than a general intention to “start a business.” If you hold an attested degree, diploma, or skill certificate — especially from a GoKP development program or an affiliated institute — keep it ready, because preference goes to applicants who can document their skill. Third, settle your guarantors before anything else, since this is the step that delays most people. Your government guarantor, who must be BPS 07 or above, needs a salary slip and a Letter of Comfort from their department that confirms their grade. Your second guarantor, if a private individual, needs documented proof of income and a signed undertaking on stamp paper. Both guarantors also need two passport-size photographs each, the same as your own submission. Arriving with all of this prepared means your application can move straight to assessment instead of waiting on missing paperwork. Submit everything together — your own documents and both guarantors’ documents in one complete file — because an application that sits idle for weeks is very often one where a guarantor’s letter arrived without the salary slip or proof of income that was supposed to accompany it.
How to Apply for Insaf Rozgar Scheme
Step-by-Step Application
- Confirm your district is currently covered — the scheme is launched in the Newly Merged Districts and FR regions specifically.
- Visit your area’s designated BOK branch or Area Office handling Insaf Rozgar applications.
- Prepare your business plan showing a clear, skills-relevant idea.
- Arrange your two guarantors in advance, ensuring one is a government employee of BPS 07 or above.
- Submit your CNIC, photographs, attested degree/diploma/skill certificate (if applicable), and all guarantor documents together.
- Sign the Agreement of Finance, Demand Promissory Note, and Personal Guarantee forms once approved.
Insaf Rozgar Scheme Loan Terms
BOK’s own page states that the exact loan size depends on assessment of your business plan under prudent banking practices, rather than a single fixed amount for everyone. Reported figures have varied across phases — earlier phases cited ranges as low as Rs. 50,000 and as high as Rs. 1 million — so confirm your current tier directly at your BOK branch rather than relying on an older figure. For new enterprises, the repayment tenor is 3 years, inclusive of a 3-month grace period before repayments begin. The loan is interest-free, consistent with BOK’s Islamic financing structure for this product.
How Insaf Rozgar Compares With Other Loan Options
Insaf Rozgar is a provincial route built for one specific applicant: an individual living in the Newly Merged Districts or FR regions who can arrange two guarantors. If your situation is different, another programme may fit you better, and applying to the wrong one costs you weeks. Applicants who do not live in the merged districts are outside this scheme’s current coverage, so a more realistic federal alternative is the PM Youth Business Loan, the federal government’s nationwide business loan programme — check its own eligibility and process on its guide before assuming it replaces this scheme. And if you are still deciding between Bank of Khyber’s own products, our KP Government Loan Scheme overview compares all three KP options side by side — group loans under Ehsaas Naujawan, individual loans under Insaf Rozgar, and salary-based financing for government employees — so you can see in one place which eligibility box you actually tick. Comparing first also matters because the structures differ in ways that affect you directly: Insaf Rozgar needs personal guarantors, the group product needs registered partners who share responsibility, and the federal programme runs through its own partner banks rather than your local BOK branch.
What to Do If Something Goes Wrong
Most rejections trace back to incomplete guarantor documentation — double-check that your government guarantor’s Letter of Comfort explicitly states their BPS grade, since a vague letter is a common rejection reason. If you’re unsure whether your district currently falls under the scheme’s active coverage, ask at your Area Office before submitting a full application. If anyone asks for a fee to “guarantee approval,” that is not part of the official process — report it to your branch manager. If your business idea itself was the issue, revising it to more clearly match a skill you can document (such as a certificate) often improves your next attempt.
A Worked Example: Repaying an Interest-Free Loan Over 3 Years
Because Insaf Rozgar loans are interest-free, the repayment maths is simpler than a conventional loan — you return the amount you borrowed, with no markup added on top. Take a new enterprise approved for Rs. 300,000. The tenor for new enterprises is 3 years, including a 3-month grace period before repayments begin, so the amount is typically spread across the remaining months of the term. Spread evenly, that works out at roughly Rs. 9,100 per month — money you can plan for from the business’s own income once the grace period ends. A smaller loan is proportionally easier: Rs. 100,000 on the same structure comes to roughly Rs. 3,000 per month over the same repayment window. These figures are an illustration of the guide’s stated terms, not a quote — your exact installment schedule is written into the Agreement of Finance you sign at approval, and your branch confirms it before disbursement. The example does show why matching the loan to your business plan matters: BOK sets the loan size by assessing what your enterprise can realistically carry, so asking for an amount your plan cannot support usually leads to a smaller approval rather than a bigger one.
Frequently Asked Questions
Is Insaf Rozgar Scheme open to all of KP or just the merged districts?
Bank of Khyber’s own criteria specify permanent residents of the Newly Merged Districts specifically. Some general news coverage describes it as province-wide, but this may reflect different or historical phases. Confirm your district’s current eligibility at your local BOK branch.
How much can I borrow under Insaf Rozgar Scheme?
There’s no single fixed amount — BOK assesses your business plan to determine loan size. Reported ranges have varied by phase, from Rs. 50,000 up to Rs. 1 million historically. Ask your branch for the currently active tier structure.
Do I need a government employee as my guarantor?
Yes, at least one of your two required guarantors must be a government employee of BPS 07 or above. Your second guarantor can be a private individual with documented income. Both need specific supporting paperwork.
What is the repayment period?
For new enterprises, it’s 3 years, including a 3-month grace period before repayments start. This is BOK’s current stated structure. Older phases of the scheme reportedly used different terms, so rely on your current loan agreement.
Is this the same as Ehsaas Naujawan Programme?
No, Ehsaas Naujawan is structured around registered partnerships of 3 to 5 people, while Insaf Rozgar is aimed at individual applicants with a personal guarantor structure. Both are BOK-administered KP schemes but serve different applicant setups. Compare both before deciding which fits your situation.
Is a business plan required even for a small loan?
Yes, BOK explicitly assesses whether your business idea is workable and skills-relevant regardless of loan size. A vague idea without documentation is a common reason for lower approved amounts or rejection. Bringing a certificate or diploma related to your business idea can strengthen your application.
Official source
Official maloomat ke liye sirf bok.com.pk (Bank of Khyber) istemal karein. AwamSchemes does not accept applications or process payments.