Khyber Pakhtunkhwa · Guide
KP Government Loan Scheme 2026: Overview
Khyber Pakhtunkhwa’s government schemes include three separate loan options for residents, and each one fits a different situation. Ehsaas Naujawan Programme (KP) gives groups of three to five people up to Rs. 5 million to launch a larger business, according to bok.com.pk. Insaf Rozgar Scheme offers smaller individual loans, but only to residents of KP’s Newly Merged Districts and FR regions. Bank of Khyber’s Salary Sahara product gives salaried government employees a personal loan of up to Rs. 2 million against their monthly pay. This guide compares all three side by side, so you can pick the one that actually fits your situation.
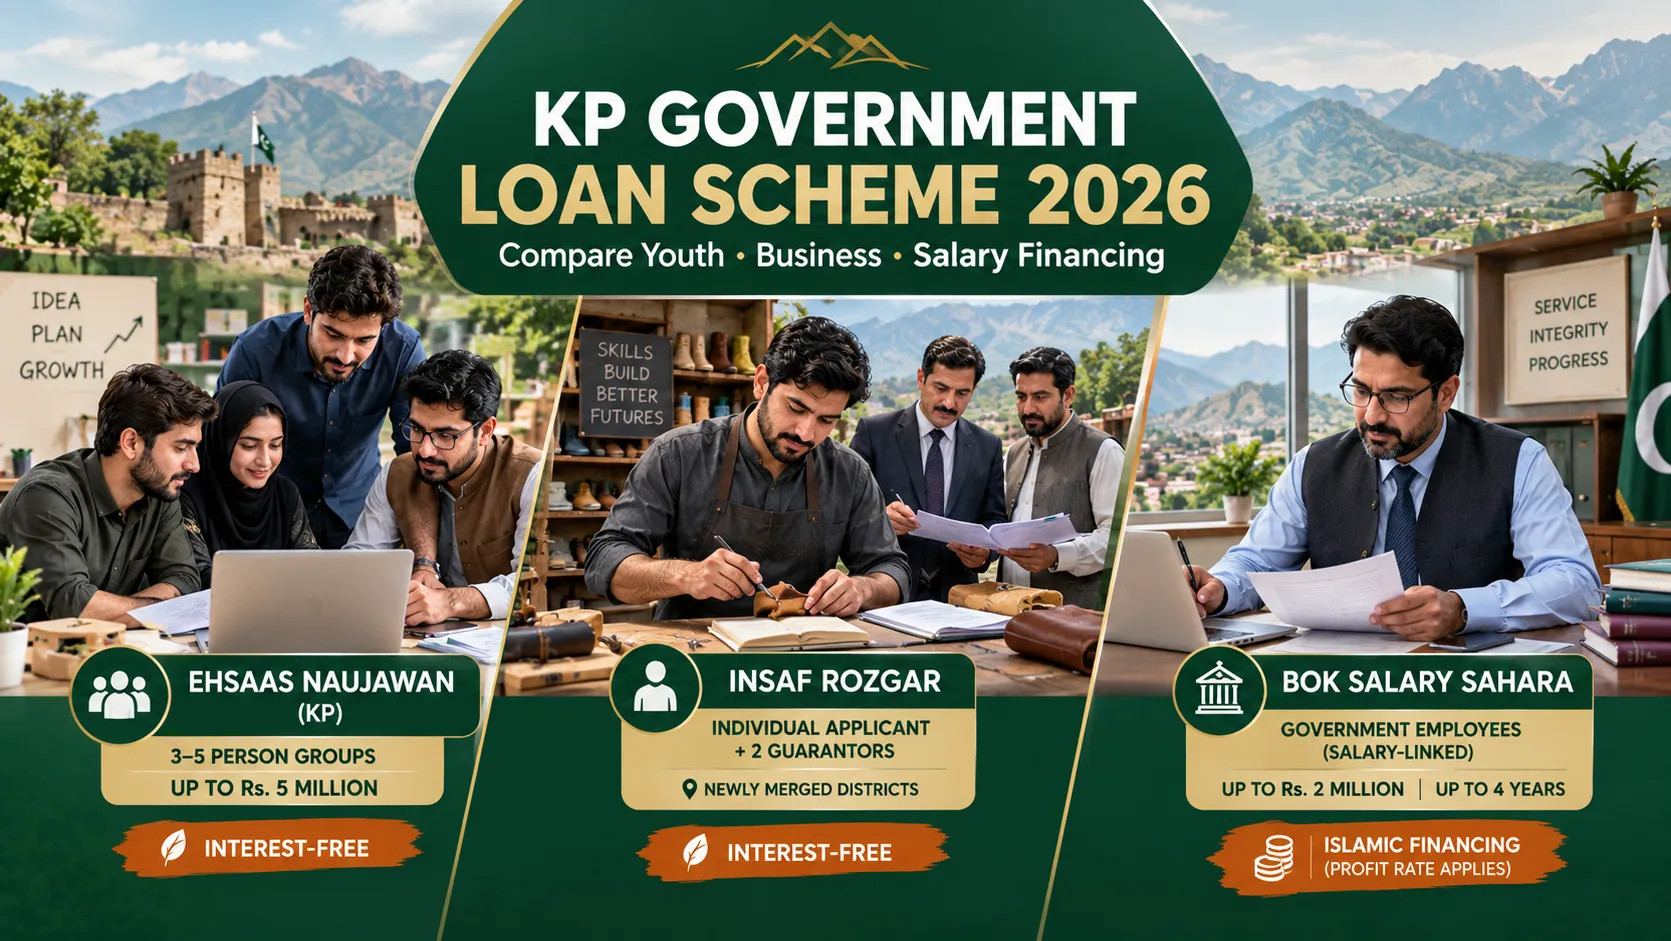
Khyber Pakhtunkhwa’s government schemes include three separate loan options for residents, and each one fits a different situation. Ehsaas Naujawan Programme (KP) gives groups of three to five people up to Rs. 5 million to launch a larger business, according to bok.com.pk. Insaf Rozgar Scheme offers smaller individual loans, but only to residents of KP’s Newly Merged Districts and FR regions. Bank of Khyber’s Salary Sahara product gives salaried government employees a personal loan of up to Rs. 2 million against their monthly pay. This guide compares all three side by side, so you can pick the one that actually fits your situation.
Key facts
- Amount / benefit
- Ehsaas Naujawan: up to Rs. 5 million per group; Insaf Rozgar: up to roughly Rs. 1 million depending on category; BOK Salary Sahara: up to Rs. 2 million for salaried government employees.
- Who qualifies
- KP residents, depending on the scheme: groups of 3–5 forming a registered firm/partnership (Ehsaas Naujawan), individuals in the Newly Merged Districts and FR regions (Insaf Rozgar), or salaried government/semi-government/autonomous body employees aged 22–59 (Salary Sahara).
- How to check / apply
- See the guide below
- Official helpline / portal
- bok.com.pk (Bank of Khyber)
Awamschemes.com is an independent information resource and has no official affiliation with the Government of Khyber Pakhtunkhwa or Bank of Khyber. For official information on these schemes, use the official Bank of Khyber portal, bok.com.pk.
Quick Comparison
| Scheme | Who It’s For & Key Terms |
|---|---|
| Ehsaas Naujawan Programme (KP) | Groups of 3–5 people forming a registered firm/partnership; Rs. 1M–5M, interest-free, up to 8 years with a 20-month grace period; open to all KP districts including merged districts |
| Insaf Rozgar Scheme | Individuals only, with 2 personal guarantors (one must be a government employee); interest-free, up to roughly Rs. 1M depending on category; restricted to Newly Merged Districts & FR regions |
| Bank of Khyber Salary Sahara (Govt Employees) | Salaried government/semi-government/autonomous body employees, age 22–59; up to 15x net salary, max Rs. 2M; up to 4 years; not interest-free, standard Islamic financing profit rate applies |
Ehsaas Naujawan Programme (KP) — For Groups Starting a Larger Business
Ehsaas Naujawan Programme (KP) gives interest-free loans of Rs. 1 million to Rs. 5 million per group, company, or association of persons, according to bok.com.pk. Applicants must form a registered firm or partnership with three to five individuals, and all partners are jointly responsible for repayment. The loan runs for up to 8 years, with a grace period of up to 20 months before repayment starts, and funds are disbursed in tranches as formalities are completed. A smaller, Akhuwat-administered component also offers interest-free loans of Rs. 100,000 to Rs. 500,000 to individuals aged 18 to 40, per the KP government’s launch announcement, reported by Business Recorder.
Insaf Rozgar Scheme — For Individuals in Newly Merged Districts
Insaf Rozgar Scheme is restricted to permanent residents of KP’s Newly Merged Districts and FR regions, according to bok.com.pk. Unlike Ehsaas Naujawan, this scheme is for individual applicants, not groups, and needs two personal guarantors, at least one of whom must be a government employee of BPS 07 or above. Loan amounts vary by category: professionally educated or skilled applicants can get up to Rs. 1 million, while general or informal applicants are capped around Rs. 300,000. The loan tenor is 3 years, including a 3-month grace period for new enterprises, and the applicant themself must not already be a government employee.
Bank of Khyber Salary Sahara — For Government Employees
Bank of Khyber’s loan scheme for government employees, branded BOK Salary Sahara, is open to all salaried employees of government, semi-government, and autonomous bodies aged 22 to 59, according to bok.com.pk. Applicants need at least one year of service and must route at least one salary through a BOK account. The loan amount equals up to 15 times the applicant’s net take-home salary, capped at Rs. 2 million, repayable over a maximum of 4 years. Unlike Ehsaas Naujawan and Insaf Rozgar, this is a standard Islamic financing product, not an interest-free government subsidy — it carries a normal profit rate under BOK’s Islamic banking structure, plus compulsory life insurance up to the loan amount.
Three Applicant Situations, Matched to the Right Scheme
The comparison table above is easier to use with real situations in mind. Situation one: three partners want to open a trading business in Peshawar and need Rs. 3 million. They fit Ehsaas Naujawan Programme — a registered partnership of 3 to 5 people can borrow Rs. 1 million to Rs. 5 million interest-free, repayable over up to 8 years with a grace period of up to 20 months, and the group shares responsibility for repayment. Situation two: a skilled technician living in a Newly Merged District needs Rs. 800,000 to set up her own workshop, applying alone. She fits the Insaf Rozgar Scheme — professionally educated or skilled applicants can get up to Rs. 1 million, while general or informal applicants are capped around Rs. 300,000, over a 3-year tenor that includes a 3-month grace period for new enterprises; she will need two personal guarantors, one a government employee of BPS 07 or above, and she must not herself be a government employee. Situation three: a government schoolteacher needs Rs. 1.2 million for a personal expense, not a business. She fits the Bank of Khyber Loan Scheme for government employees (BOK Salary Sahara) — up to 15 times net take-home salary, capped at Rs. 2 million, over up to 4 years — provided her net salary supports the amount and at least one salary is routed through a BOK account. Notice that in all three situations the deciding factors are the same: where you live, whether you apply alone or as a group, and whether the money is for a business or for personal use.
Which Scheme Should You Apply For?
If you and a few partners want to launch a larger business anywhere in KP, Ehsaas Naujawan Programme fits best. If you live in a Newly Merged District or FR region and need a smaller individual loan, Insaf Rozgar Scheme is the closer match. If you’re a government employee who needs a personal loan against your salary rather than a business loan, Bank of Khyber’s Salary Sahara is the right option.
Before You Visit the Branch: A Quick Self-Check
Five minutes of checking against the three schemes’ basic conditions can save you a wasted trip. Ask yourself, in order: Where do I live? Insaf Rozgar is restricted to the Newly Merged Districts and FR regions, while Ehsaas Naujawan covers all KP districts. Am I applying alone or with partners? Ehsaas Naujawan’s main track requires a registered firm or partnership of 3 to 5 people; Insaf Rozgar is for individuals; Salary Sahara is for a single salaried employee. Do I have a government job? Salary Sahara requires at least a year of service with a government, semi-government, or autonomous body and an age between 22 and 59 — while Insaf Rozgar applicants must not already be government employees themselves. Can I meet the guarantee structure? Insaf Rozgar needs two personal guarantors with one at BPS 07 or above; Ehsaas Naujawan partners are jointly responsible instead. Is the amount I need inside the scheme’s range? Roughly Rs. 1 million or less points to Insaf Rozgar, Rs. 1 to 5 million for a group points to Ehsaas Naujawan, and a personal need tied to your salary points to Salary Sahara. If your answers point in two directions at once, take both questions to your nearest BOK branch — the branch can confirm which eligibility you actually meet before you file anything.
What to Do If Your Application Is Rejected
Each scheme has its own guarantor and residency requirements, so a rejection under one scheme doesn’t rule out the others. Check whether your business location, group size, or district falls inside the specific scheme’s eligibility before reapplying elsewhere. For any of these three, the nearest Bank of Khyber branch can explain the exact reason for a rejected application and confirm whether you qualify for a different option.
Repayment Timelines at a Glance
Because all three schemes come from the same bank, applicants often assume their repayment clocks work the same way — they do not. Ehsaas Naujawan gives the longest runway: up to 8 years in total, with a grace period of up to 20 months before repayments start, and funds are disbursed in tranches as formalities are completed rather than in one payment. That structure suits a group business that needs time to become profitable before installments begin. Insaf Rozgar runs much shorter: a 3-year tenor for new enterprises, including a 3-month grace period, which suits a smaller individual loan that starts generating income quickly. Salary Sahara allows a maximum of 4 years through fixed monthly installments, and since it is a standard Islamic financing product rather than an interest-free subsidy, a normal profit rate applies on top of the principal — the only one of the three where the amount you repay is more than the amount you borrowed. When you compare offers, compare the full picture: a longer tenor lowers each installment but keeps you in debt longer, while a grace period only helps if your business genuinely starts earning within it. One more difference is easy to miss: the two interest-free schemes are government initiatives run through the bank, while Salary Sahara is a regular Bank of Khyber financing product — which is why its approval turns on your salary and service record rather than on district coverage, group size, or a business plan.
Frequently Asked Questions
Which KP loan scheme is completely interest-free?
Ehsaas Naujawan Programme and Insaf Rozgar Scheme are both interest-free, since they’re government-subsidized initiatives run through Bank of Khyber. Bank of Khyber’s Salary Sahara product for government employees is a standard Islamic financing product and carries a normal profit rate.
Can I apply for Insaf Rozgar Scheme if I don’t live in a Newly Merged District?
No. Insaf Rozgar Scheme is currently restricted to permanent residents of KP’s Newly Merged Districts and FR regions, according to bok.com.pk. Residents of other KP districts should check Ehsaas Naujawan Programme instead.
How much can I borrow under Ehsaas Naujawan Programme?
Groups of three to five people can borrow between Rs. 1 million and Rs. 5 million, depending on the business plan and applicant capability. The loan is repayable over up to 8 years, with a grace period of up to 20 months.
Do I need a guarantor for these loan schemes?
Insaf Rozgar Scheme requires two personal guarantors, and at least one must be a government employee of BPS 07 or above. Ehsaas Naujawan Programme instead requires all partners in the registered firm to be jointly responsible for the loan.
Is Bank of Khyber’s Salary Sahara only for KP government employees?
No. It’s open to salaried employees of government, semi-government, and autonomous bodies generally, not only KP provincial government staff. Applicants must be aged 22 to 59 with at least one year of service.
What happens if my loan application under one scheme is rejected?
You can apply for a different scheme if your profile fits its specific eligibility criteria. Visit your nearest Bank of Khyber branch to get the exact reason for the rejection before reapplying.
Official source
Official maloomat ke liye sirf bok.com.pk (Bank of Khyber) istemal karein. AwamSchemes does not accept applications or process payments.